Introduction
Accurate markup calculations are essential for small businesses that want to price products competitively while protecting profitability. Whether you operate an online store, retail shop, wholesale company, or manufacturing business in the United States, your pricing decisions directly affect revenue, cash flow, and long-term growth.
A basic markup formula adds a percentage to a product’s cost. However, advanced pricing requires more than multiplying cost by a percentage. Businesses must account for shipping, packaging, payment processing, discounts, returns, overhead, and changes in supplier prices.
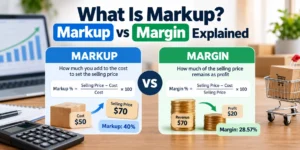
Another common challenge is confusing markup with profit margin. A 40% markup does not produce a 40% gross profit margin. Using the wrong formula can lead to prices that appear profitable but fail to cover business expenses.
This guide explains advanced markup calculations for small businesses, with practical examples, formulas, and US business considerations. It also shows how a markup calculator can simplify pricing decisions when used alongside accurate cost records and regular financial reviews.
What Are Markup Calculations?
Markup calculations determine how much to add to a product’s cost to establish a selling price.
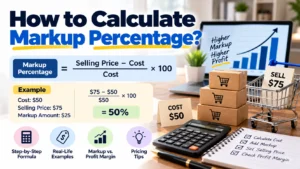
The basic formula is:
Markup Percentage = (Selling Price − Cost) ÷ Cost × 100
To calculate the selling price from a known cost and markup percentage, use:
Selling Price = Cost × (1 + Markup Percentage ÷ 100)
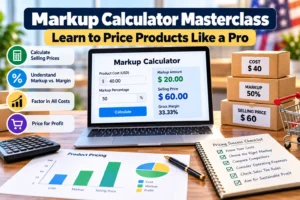
For example, suppose a small retailer purchases a product for $40 and applies a 50% markup.
- Product cost: $40
- Markup amount: $20
- Selling price: $60
The $20 difference is the amount remaining after subtracting the stated product cost from the selling price. It is not necessarily net profit because the business may still have operating expenses and other costs to cover.
Advanced markup calculations improve this process by using a more complete understanding of the costs associated with selling each product.
1. Calculate Your True Unit Cost
One of the most important advanced pricing techniques is establishing a reliable cost per unit before applying markup.
A product’s purchase price may not represent its full economic cost. Depending on the business, additional costs may include inbound freight, packaging, direct labor, production materials, customs duties, and other expenses associated with acquiring or manufacturing the product.
Consider this example for a US online retailer:
| Cost component | Cost per unit |
| Wholesale product cost | $25.00 |
| Inbound shipping | $2.00 |
| Packaging | $1.50 |
| Direct handling labor | $1.50 |
| Total listed unit cost | $30.00 |
If the retailer applies a 50% markup to the $25 wholesale price, the calculated selling price is $37.50.
However, applying the same markup to the $30 cost base produces a selling price of $45.
The second calculation reflects the additional listed costs, although the appropriate cost base depends on your pricing objective and accounting method.
Best practice: Maintain separate records for inventory cost, fulfillment costs, payment fees, and overhead. This allows you to calculate accounting gross margin correctly while also evaluating the total economics of each sale.
The IRS explains the importance of maintaining records for inventory, business expenses, and income in Publication 583: Starting a Business and Keeping Records.
2. Use the Correct Formula for Your Target Gross Margin
Businesses often choose prices based on a target gross margin rather than a target markup.
Markup measures the increase relative to cost, while gross margin measures the difference between selling price and cost as a percentage of selling price.
The gross margin formula is:
Gross Margin = (Selling Price − Cost) ÷ Selling Price × 100
To calculate a selling price from a target gross margin:
Selling Price = Cost ÷ (1 − Target Gross Margin)
The target margin must be entered as a decimal in the formula.
Example: Target a 40% Gross Margin
Suppose your relevant product cost is $60 and you want a 40% gross margin.
Selling Price = $60 ÷ (1 − 0.40)
Selling Price = $60 ÷ 0.60 = $100
The selling price must be $100 to produce a $40 difference between selling price and cost.
That represents a 66.67% markup on the $60 cost.
| Cost | Pricing target | Selling price | Difference before other expenses |
| $60 | 30% gross margin | $85.71 | $25.71 |
| $60 | 40% gross margin | $100.00 | $40.00 |
| $60 | 50% gross margin | $120.00 | $60.00 |
These examples assume the same $60 cost base for each calculation. Gross margin is not net profit margin because operating expenses may still need to be deducted.
3. Account for Payment Processing and Variable Selling Costs
For online stores, the amount a business receives from a sale may be lower than the listed selling price because of payment processing fees, marketplace commissions, fulfillment expenses, and shipping subsidies.
These costs can materially affect pricing.
Suppose a product costs $30 and the seller expects the following additional expenses:
- Fulfillment: $4 per order.
- Packaging not already included in product cost: $1 per order.
- Payment processing: 3% of the selling price.
Assume the seller wants a contribution of $15 per unit after these listed costs.
The price must cover the $30 product cost, $4 fulfillment, $1 packaging, $15 desired contribution, and a payment fee equal to 3% of the selling price.
The formula is:
Selling Price = (Product Cost + Other Fixed Per-Unit Costs + Desired Contribution) ÷ (1 − Variable Fee Rate)
Substituting the values:
Selling Price = ($30 + $4 + $1 + $15) ÷ (1 − 0.03)
Selling Price = $50 ÷ 0.97 = $51.55 approximately
At a selling price of $51.55, a 3% payment fee is approximately $1.55. After the listed costs, about $15 remains as the desired contribution.
This example excludes other expenses such as advertising, returns, rent, and taxes on business income. Include additional variable costs when they apply, and avoid counting the same cost twice.
4. Include Overhead in Your Pricing Decisions
Small businesses often focus on direct product costs and overlook overhead. Expenses such as rent, utilities, insurance, accounting, software, and administrative salaries still need to be funded by sales.
One approach is to estimate overhead per unit using expected sales volume.
Estimated Overhead per Unit = Total Allocated Overhead ÷ Expected Units Sold
Suppose your business expects $12,000 in monthly overhead and plans to sell 2,000 units.
$12,000 ÷ 2,000 = $6 per unit.
The business could use this $6 estimate as part of an internal pricing analysis. However, overhead allocation is a management estimate and should not automatically be treated as the product’s accounting cost under every accounting method.
Why Sales Volume Matters
If the business sells only 1,500 units, the same $12,000 overhead equals $8 per unit. At 2,500 units, it equals $4.80 per unit.
This demonstrates why a price that works at expected sales volume may become less profitable if sales fall.
For a deeper analysis, the US Small Business Administration’s break-even guide explains how fixed costs, variable costs, and selling prices influence profitability.
5. Use Break-Even Analysis Before Setting a Final Price
Break-even analysis estimates how many units a business must sell to cover its fixed costs.
The basic formula is:
Break-Even Units = Fixed Costs ÷ Contribution per Unit
Contribution per unit is the selling price minus variable costs per unit. The result is the amount available to cover fixed costs and then contribute to profit.
Suppose a small business has:
- Monthly fixed costs: $6,000.
- Selling price: $50 per unit.
- Variable cost per unit: $30.
Contribution per unit = $50 − $30 = $20.
Break-even units = $6,000 ÷ $20 = 300 units per month.
The business must sell approximately 300 units per month to cover the stated fixed and variable costs, assuming the figures remain accurate and the product is the only relevant source of contribution.
If the business reduces its selling price to $45 while variable costs remain $30, contribution falls to $15.
Break-even units = $6,000 ÷ $15 = 400 units.
A $5 price reduction therefore increases the estimated break-even volume from 300 to 400 units. This is why discounts should be evaluated against contribution and expected sales volume, not revenue alone.
The SBA provides a break-even point calculator that businesses can use to explore these relationships.
6. Calculate Markup After Discounts and Promotions
A product’s list price may not be the price customers ultimately pay. Coupons, seasonal discounts, bundle offers, and loyalty promotions reduce the actual selling price.
To calculate the price after a discount:
Discounted Price = List Price × (1 − Discount Rate)
Suppose a product costs $40 and is listed at $70. The business offers a 20% discount.
Discounted Price = $70 × (1 − 0.20) = $56.
The difference between the discounted price and the $40 cost is $16.
Markup on the original cost after the discount is:
($56 − $40) ÷ $40 × 100 = 40%.
Although the original list price represented a 75% markup, the actual transaction produces a 40% markup before other expenses.
Set a Minimum Price for Promotions
If your business frequently runs promotions, calculate the minimum acceptable selling price before launching the campaign.
For example, if the product costs $40 and you require at least a 25% markup on that cost, the minimum price under this simplified requirement is:
$40 × 1.25 = $50.
If you offer a 20% discount, the list price must be at least:
$50 ÷ 0.80 = $62.50.
This ensures that the discounted selling price reaches $50, assuming the $40 cost base is complete for the markup target. If other variable costs apply, include them in a broader contribution analysis.
7. Adjust Markup for Returns, Waste, and Damaged Inventory
Businesses selling physical goods may experience product returns, damage, spoilage, shrinkage, or unsold inventory. Ignoring these factors can make a pricing model overly optimistic.
For example, a retailer may purchase 100 units for $20 each, spending $2,000. If five units become unsellable and the remaining 95 units must recover the entire purchase cost, the effective purchase cost per sellable unit becomes:
$2,000 ÷ 95 = $21.05 approximately.
This does not automatically determine the correct accounting treatment for damaged or obsolete inventory. It illustrates how losses can increase the effective cost of the units that remain available for sale.
Use historical data to estimate return rates, damage rates, and other recurring losses. Avoid adding arbitrary percentages without evidence, and review the estimates when product quality or supplier performance changes.
8. Use Different Markup Strategies for Different Products
Applying the same markup percentage to every product is simple, but it may not fit the economics of every product category.
A business could use different pricing approaches for:
- High-volume products with strong price competition.
- Specialty products with distinctive features.
- Fragile items with higher shipping or return costs.
- Low-volume products with substantial storage or handling expenses.
- Bundles that encourage customers to buy multiple items.
For example, a basic accessory may require competitive pricing because customers can compare many similar products. A specialized product may support a different price if customers value its quality, convenience, or performance.
The key is to use product-level cost information and market research rather than relying on a single markup percentage across the entire catalog.
9. Consider US Sales Tax Separately
US sales tax requirements vary by state and, in some locations, by local jurisdiction. Taxability, collection obligations, and rates depend on the product or service, where the transaction occurs, and the seller’s circumstances.
Businesses should generally separate the selling price from sales tax collected from customers. Sales tax collected for remittance should not automatically be treated as product revenue or markup.
For example, if a taxable product sells for $100 and the applicable sales tax rate is 7%, the customer pays $107. The $7 tax amount is collected under the applicable rules and is not an additional $7 of product markup.
This is a simplified illustration; actual tax treatment and collection requirements vary. Businesses should confirm their obligations with the relevant state tax authority. The Texas Comptroller’s sales tax resources provide an example of state-specific guidance.
Also distinguish sales tax from federal and state income taxes on business profits. Do not simply add a generic income-tax percentage to each product’s markup and assume that it accurately calculates tax liability.
10. Automate and Review Your Markup Calculations
As the number of products grows, manual calculations become more prone to errors. A spreadsheet, accounting platform, or pricing system can help standardize cost inputs and update prices when supplier costs change.
A reliable pricing workflow should include:
- Recording current supplier and production costs.
- Separating direct costs, variable selling costs, and overhead.
- Selecting a target markup or gross margin.
- Calculating a preliminary selling price.
- Checking discounts, payment fees, and contribution.
- Reviewing market prices and customer demand.
- Documenting the final price and the assumptions behind it.
The IRS emphasizes the value of accurate records for tracking income and expenses and preparing financial statements. See its small business recordkeeping guidance.
A markup calculator can speed up the arithmetic, but the quality of the result depends on the quality of the information entered.
Common Markup Calculation Mistakes
Avoid these frequent errors when developing a pricing strategy:
- Confusing markup with margin: The two percentages use different denominators.
- Ignoring variable selling costs: Fees, shipping subsidies, and returns may reduce contribution.
- Overlooking overhead: A positive product-level difference does not guarantee overall business profit.
- Using outdated cost data: Supplier increases can erode margins if prices are not updated.
- Ignoring discounts: The realized price may be substantially lower than the list price.
- Treating sales tax as revenue: Tax collected from customers should be handled according to applicable rules.
- Assuming every product needs the same markup: Product economics and market conditions vary.
Frequently Asked Questions
What is the best formula for markup calculations?
The standard formula is:
Markup Percentage = (Selling Price − Cost) ÷ Cost × 100
To calculate the selling price from a target markup:
Selling Price = Cost × (1 + Markup Percentage ÷ 100)
The formula is useful when the cost base and markup target are clearly defined.
How do I calculate markup for a 40% profit margin?
If you want a 40% gross margin, divide the relevant cost by 0.60.
For example, a $60 cost requires a $100 selling price to achieve a 40% gross margin before other expenses. A 40% markup would produce a different price.
Should I include shipping in markup calculations?
Include shipping when it is part of your chosen cost base or affects the economics of the sale. Inbound freight may be treated differently from outbound fulfillment for accounting purposes, so keep records that distinguish these costs.
How often should small businesses update prices?
Review pricing whenever material costs change and at regular intervals appropriate to your business. High-volume businesses with fluctuating supplier costs may need more frequent reviews than businesses with stable prices and long-term contracts.
Can a markup calculator determine my net profit?
No. A markup calculator performs calculations based on the inputs provided. Estimating net profit requires a broader view of revenue, cost of goods sold, operating expenses, taxes, and other financial items.
Conclusion
Accurate markup calculations help small businesses establish more informed prices, protect contribution, and understand how changes in cost or discounts affect profitability.
The most effective approach begins with reliable unit-cost data and uses the correct formula for the intended goal. Businesses should distinguish markup from gross margin, account for relevant variable costs, review overhead, and use break-even analysis to test whether their pricing can support their operations.
US small businesses should also maintain appropriate financial records and evaluate applicable sales tax obligations separately from product pricing.
Use the CalcZest Markup Calculator to calculate a starting selling price, then test that price against your complete cost structure, business goals, and market conditions.
Disclaimer: This article is for general educational purposes only and is not accounting, tax, legal, or financial advice. Cost classification and sales tax obligations vary by business and jurisdiction. Consult a qualified accountant or tax professional for advice specific to your business.