Employee stock compensation can be an important part of your total pay, particularly if you work for a startup, a publicly traded company, or a business that offers equity incentives. However, understanding what your shares are actually worth can be confusing. The number of shares you own does not necessarily tell you how much money you could receive from them.
To calculate employee share value, you need to understand your company’s share price, the type of equity you hold, your vesting schedule, and any restrictions that affect when you can sell your shares. Taxes, exercise costs, and potential changes in the company’s valuation can also influence the financial outcome.
This guide explains how to calculate employee share value, compare different types of employee equity, and estimate what your shares could be worth under US rules.
What Is Employee Share Value?
Employee share value is the estimated monetary value of shares or equity awards an employee receives through an employer’s compensation program.
Companies may offer equity as part of an employee compensation package to reward performance, encourage retention, or align employees’ interests with the company’s long-term growth.
Employee equity can take several forms:
- Restricted Stock Units (RSUs): A promise to deliver company shares or their cash equivalent when specified conditions are satisfied.
- Employee stock options: The right to purchase company shares at a predetermined exercise price.
- Restricted stock: Actual shares granted to an employee, usually subject to vesting or forfeiture restrictions.
- Employee Stock Purchase Plans (ESPPs): Programs that allow eligible employees to purchase company stock, often through payroll deductions and sometimes at a discount.
These arrangements are not interchangeable. For example, an RSU may have value when it vests, while an unexercised stock option can be worthless if the market price falls below its exercise price.
Understanding your particular equity award is the first step toward calculating its value accurately.
How to Calculate Employee Share Value
The simplest calculation multiplies the number of shares by the value of each share.
Basic formula:
Employee Share Value = Number of Shares × Value Per Share
For example, suppose your employer grants you 500 shares, and each share is worth $40.
Employee share value = 500 × $40 = $20,000.
Your shares have a calculated value of $20,000 based on that per-share price.
However, this is not necessarily the amount you will receive in cash. You must account for vesting, restrictions, exercise costs, taxes, and whether a sale is possible.
Step 1: Determine the Number of Shares You Own
Start by reviewing your equity award agreement or employee stock plan account.
Identify the number of shares granted to you and distinguish between:
- Total shares granted.
- Shares that have vested.
- Shares that remain unvested.
- Shares already sold or transferred.
- Stock options that have been exercised.
- Stock options that remain unexercised.
For example, imagine that your employer grants you 1,000 RSUs, but only 400 have vested.
If the current share price is $50, the value of your vested shares is:
400 × $50 = $20,000.
The remaining 600 unvested RSUs represent a potential future value of $30,000 at the same share price, but that amount depends on future vesting and the share price at that time.
Step 2: Find the Current Share Price or Appropriate Valuation
The next step is to determine which per-share value applies to your equity award.
For publicly traded companies, you can generally find the stock’s market price through a stock exchange, brokerage account, or the company’s investor relations website.
For private companies, valuation is more complicated because their shares do not trade on a public stock exchange.
Private companies may use a 409A valuation to establish the fair market value of their common stock for certain tax purposes. This valuation is particularly relevant when determining the exercise price of many employee stock options.
However, a 409A valuation is not necessarily the same as the company’s preferred stock price from its latest fundraising round. Different share classes can have different economic rights and values.
Use the appropriate value for the type of equity you hold rather than assuming every company share has the same price.
Step 3: Multiply the Share Count by the Per-Share Value
Once you know the number of relevant shares and their estimated value, multiply them together.
Consider an employee who holds 750 vested shares valued at $32 each.
750 × $32 = $24,000.
The estimated gross value is $24,000.
This calculation provides a starting point for understanding your equity compensation. It does not account for taxes, selling restrictions, or other financial obligations.
Step 4: Account for Vesting Conditions
Many employee equity awards vest over time.
A company might use a four-year vesting schedule, with an initial one-year cliff followed by monthly vesting. The actual schedule depends on the award agreement.
Suppose an employee receives 1,200 RSUs under a four-year schedule with equal annual vesting.
If one-quarter of the award vests each year, the employee receives 300 vested RSUs annually, assuming continued employment and satisfaction of the award’s conditions.
At a share price of $40, the first year’s vested shares would have a gross value of:
300 × $40 = $12,000.
The remaining unvested shares should not be treated as guaranteed compensation because the employee may need to satisfy additional conditions before receiving them.
How to Calculate Employee Stock Option Value
Stock options require a different calculation because they give employees the right to purchase shares at a specified exercise price.
The basic formula for the intrinsic value of an option is:
Option Value = Number of Options × Max(Current Share Price − Exercise Price, 0)
The zero ensures that intrinsic value cannot be negative.
For example, suppose you have 1,000 vested options with an exercise price of $15 per share. The company’s current common stock fair market value is $35 per share.
The calculation is:
- Current share value: $35.
- Exercise price: $15.
- Difference per option: $20.
- Number of options: 1,000.
- Total intrinsic value: $20,000.
Although the intrinsic value is $20,000, exercising all 1,000 options would require $15,000 to purchase the shares, before considering any applicable taxes or fees.
The shares would have an indicated gross value of $35,000 at the assumed price, less the $15,000 exercise cost.
However, private-company options may be subject to transfer restrictions, expiration dates, and limited liquidity. You might not be able to sell the resulting shares immediately.
Additionally, intrinsic value is not the same as the full theoretical value of an option, which may include time value and other factors.
How to Calculate RSU Value
Restricted Stock Units are commonly used by publicly traded companies and some private businesses.
An RSU generally represents a contractual promise to deliver shares or cash when the applicable vesting conditions are met.
The basic calculation is:
Gross RSU Value = Number of Vested RSUs × Share Price
For example, an employee has 250 vested RSUs, and the stock trades at $80 per share.
250 × $80 = $20,000.
The gross value is $20,000 before applicable taxes and other adjustments.
For US employees, RSUs are generally taxed as ordinary compensation when they settle, subject to the specific award terms and applicable tax rules. Public-company RSUs commonly settle in shares, with some shares withheld or sold to cover taxes.
The amount eventually available to invest or spend may therefore be lower than the gross award value.
You can review the IRS’s official guidance on taxable fringe benefits and employee compensation for additional information.
How to Calculate the Value of Private Company Shares
Calculating employee share value at a private company can be more challenging than valuing publicly traded stock.
Private companies do not have continuously quoted public market prices, and their equity may be subject to contractual restrictions.
A company might have raised money from investors at a $100 million valuation, but that does not automatically mean employee common shares are worth the same amount per share as investor preferred shares.
Preferred stock may include rights such as liquidation preferences or other protections that common stock does not have.
To estimate private-company employee share value, consider the following factors:
- The company’s current common stock fair market value.
- The number of shares or equity awards you hold.
- Your vesting status.
- The type and class of equity.
- Any exercise price associated with stock options.
- Transfer restrictions and potential liquidity events.
- Applicable taxes and transaction costs.
For example, suppose you own 2,000 vested common shares with an estimated fair market value of $8 per share.
The estimated share value is:
2,000 × $8 = $16,000.
This represents an estimated value, not a guaranteed sale price. The actual proceeds could differ significantly if the company is acquired, completes an initial public offering, conducts a tender offer, or experiences financial difficulties.
Private-company equity should therefore be evaluated using the company’s actual equity terms and a realistic assessment of liquidity.
Employee Share Value Calculator Example
Use the following example to estimate the gross value of your employee shares.
| Input | Example |
| Total shares granted | 1,000 |
| Vested shares | 600 |
| Estimated price per share | $25 |
| Gross value of vested shares | $15,000 |
| Gross value of all granted shares at the same price | $25,000 |
The calculation for vested shares is:
600 × $25 = $15,000.
The remaining 400 unvested shares have an indicative value of $10,000 at the assumed price. However, this is only a hypothetical estimate because those shares may vest later, when the share price could be higher or lower.
For stock options, the calculation must also subtract the exercise price. For RSUs, the relevant tax treatment generally depends on when the units settle and the award’s terms.
How Taxes Affect Employee Share Value in the United States
Taxes can significantly affect the economic value of employee equity.
The treatment depends on the type of award, when it vests or is exercised, when shares are sold, and the employee’s individual circumstances.
RSUs and Restricted Stock
RSUs are generally taxed as ordinary compensation when the shares or cash are delivered under the award’s settlement terms.
Restricted stock can have different tax treatment. In certain circumstances, an employee may make an election under Section 83(b) of the Internal Revenue Code, generally within 30 days after the property is transferred.
An 83(b) election is not automatically available or appropriate for every equity award. RSUs generally do not qualify because the employee has not yet received the underlying property.
Nonqualified Stock Options
Nonqualified stock options (NSOs or NQSOs) generally create ordinary compensation income when exercised equal to the difference between the stock’s fair market value and the exercise price, subject to applicable rules.
A later sale can produce a capital gain or loss based on the difference between the sale proceeds and the applicable tax basis.
Incentive Stock Options
Incentive stock options (ISOs) can receive special federal tax treatment if statutory requirements are satisfied.
However, exercising ISOs can trigger alternative minimum tax (AMT) considerations even when the shares have not been sold. The eventual tax outcome depends on the circumstances and holding periods.
Capital Gains and Losses
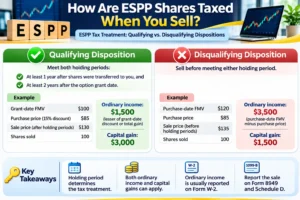
When shares are sold, the difference between the sale proceeds and the tax basis may produce a capital gain or loss.
The applicable holding period and other tax rules determine whether the gain or loss is treated as short-term or long-term.
For more information, consult the IRS resources on incentive stock options and capital gains and losses.
Because equity compensation can involve complex tax consequences, consider consulting a qualified tax professional before exercising options or selling a significant amount of company stock.
Common Mistakes When Calculating Employee Share Value
Even a simple calculation can be misleading when important details are overlooked.
1. Counting unvested shares as guaranteed value
Unvested awards may be forfeited if employment or other conditions are not satisfied. Separate vested equity from future potential awards.
2. Ignoring stock option exercise costs
The gross market value of option shares is not the same as their net economic value. Deduct the exercise price when estimating intrinsic value.
3. Treating a private company’s valuation as cash
An estimated valuation does not mean you can immediately sell your shares at that price. Liquidity restrictions and share-class differences matter.
4. Forgetting taxes
The amount you retain after taxes may be substantially lower than the gross award value. Tax withholding also may not cover your final tax liability.
5. Assuming the share price will remain unchanged
Employee share value can change with market conditions, company performance, dilution, and other factors. Future share prices are uncertain.
6. Confusing the number of shares with ownership percentage
A large share count does not necessarily represent a large ownership stake. To estimate your ownership percentage, you need the relevant total share count or fully diluted share count, depending on the purpose of the calculation.
How to Track Your Employee Share Value
Review your equity compensation regularly rather than relying on the original grant value.
Start by checking your employer’s equity management platform, award agreement, vesting schedule, and latest available share valuation.
For public-company stock, verify the current market price and distinguish vested shares from unvested awards. For private-company equity, ask whether a recent common-stock valuation or liquidity event provides relevant information.
Maintain a record of grant dates, vesting dates, option exercise prices, exercise transactions, tax documents, and share sales.
If you are considering exercising options, review the expiration date, post-termination exercise window, exercise costs, and potential tax consequences before making a decision.
You should also consider concentration risk. If a significant portion of your wealth depends on your employer, your income and investments could be affected by the same company’s performance.
A financial professional can help you assess how your equity fits into your broader financial circumstances.
Frequently Asked Questions
Is employee share value the same as salary?
No. Salary is cash compensation paid for your work, while employee share value represents the estimated value of equity awards or shares. Equity may be subject to vesting, restrictions, market fluctuations, and taxes.
How do I calculate the value of 1,000 employee shares?
Multiply 1,000 by the applicable per-share value. If each share is worth $20, the gross indicated value is $20,000. The actual realizable value may differ depending on restrictions, taxes, and transaction costs.
Are employee shares taxed in the US?
Employee shares can be subject to federal income tax, payroll taxes, and potentially state or local taxes, depending on the award type and circumstances. RSUs, restricted stock, NSOs, and ISOs can have different tax rules.
Can private-company employee shares be sold immediately?
Not necessarily. Private-company shares may be subject to transfer restrictions, company approval requirements, securities laws, and limited opportunities for liquidity. Review the applicable equity documents before assuming you can sell.
What is the difference between fair market value and share price?
For publicly traded stock, the quoted market price is a common starting point for valuation. For private-company stock, fair market value is an estimate determined using an appropriate valuation methodology. The two concepts are related but are not always interchangeable.
Does employee share value guarantee future profit?
No. Share value can rise or fall, and private-company equity may never become liquid. Even shares with a current positive estimated value can produce a loss depending on the purchase price, exercise costs, taxes, and eventual sale price.
Conclusion
Calculating employee share value begins with a straightforward formula: multiply the number of relevant shares by the appropriate per-share value. However, a reliable estimate requires more than basic multiplication.
You must identify your equity type, confirm which shares have vested, use an appropriate valuation, and account for exercise costs, restrictions, and taxes.
For publicly traded companies, current market prices provide a useful reference point. For private companies, the common-stock valuation and the possibility of a future liquidity event are particularly important.
By reviewing your award documents and understanding the applicable US tax rules, you can make a more informed assessment of your equity compensation without confusing an estimated paper value with money you can actually receive.